
European Banks/ In search of the marginal buyer
Decent 1Q reporting season, stable estimates, looking for marginal buyers
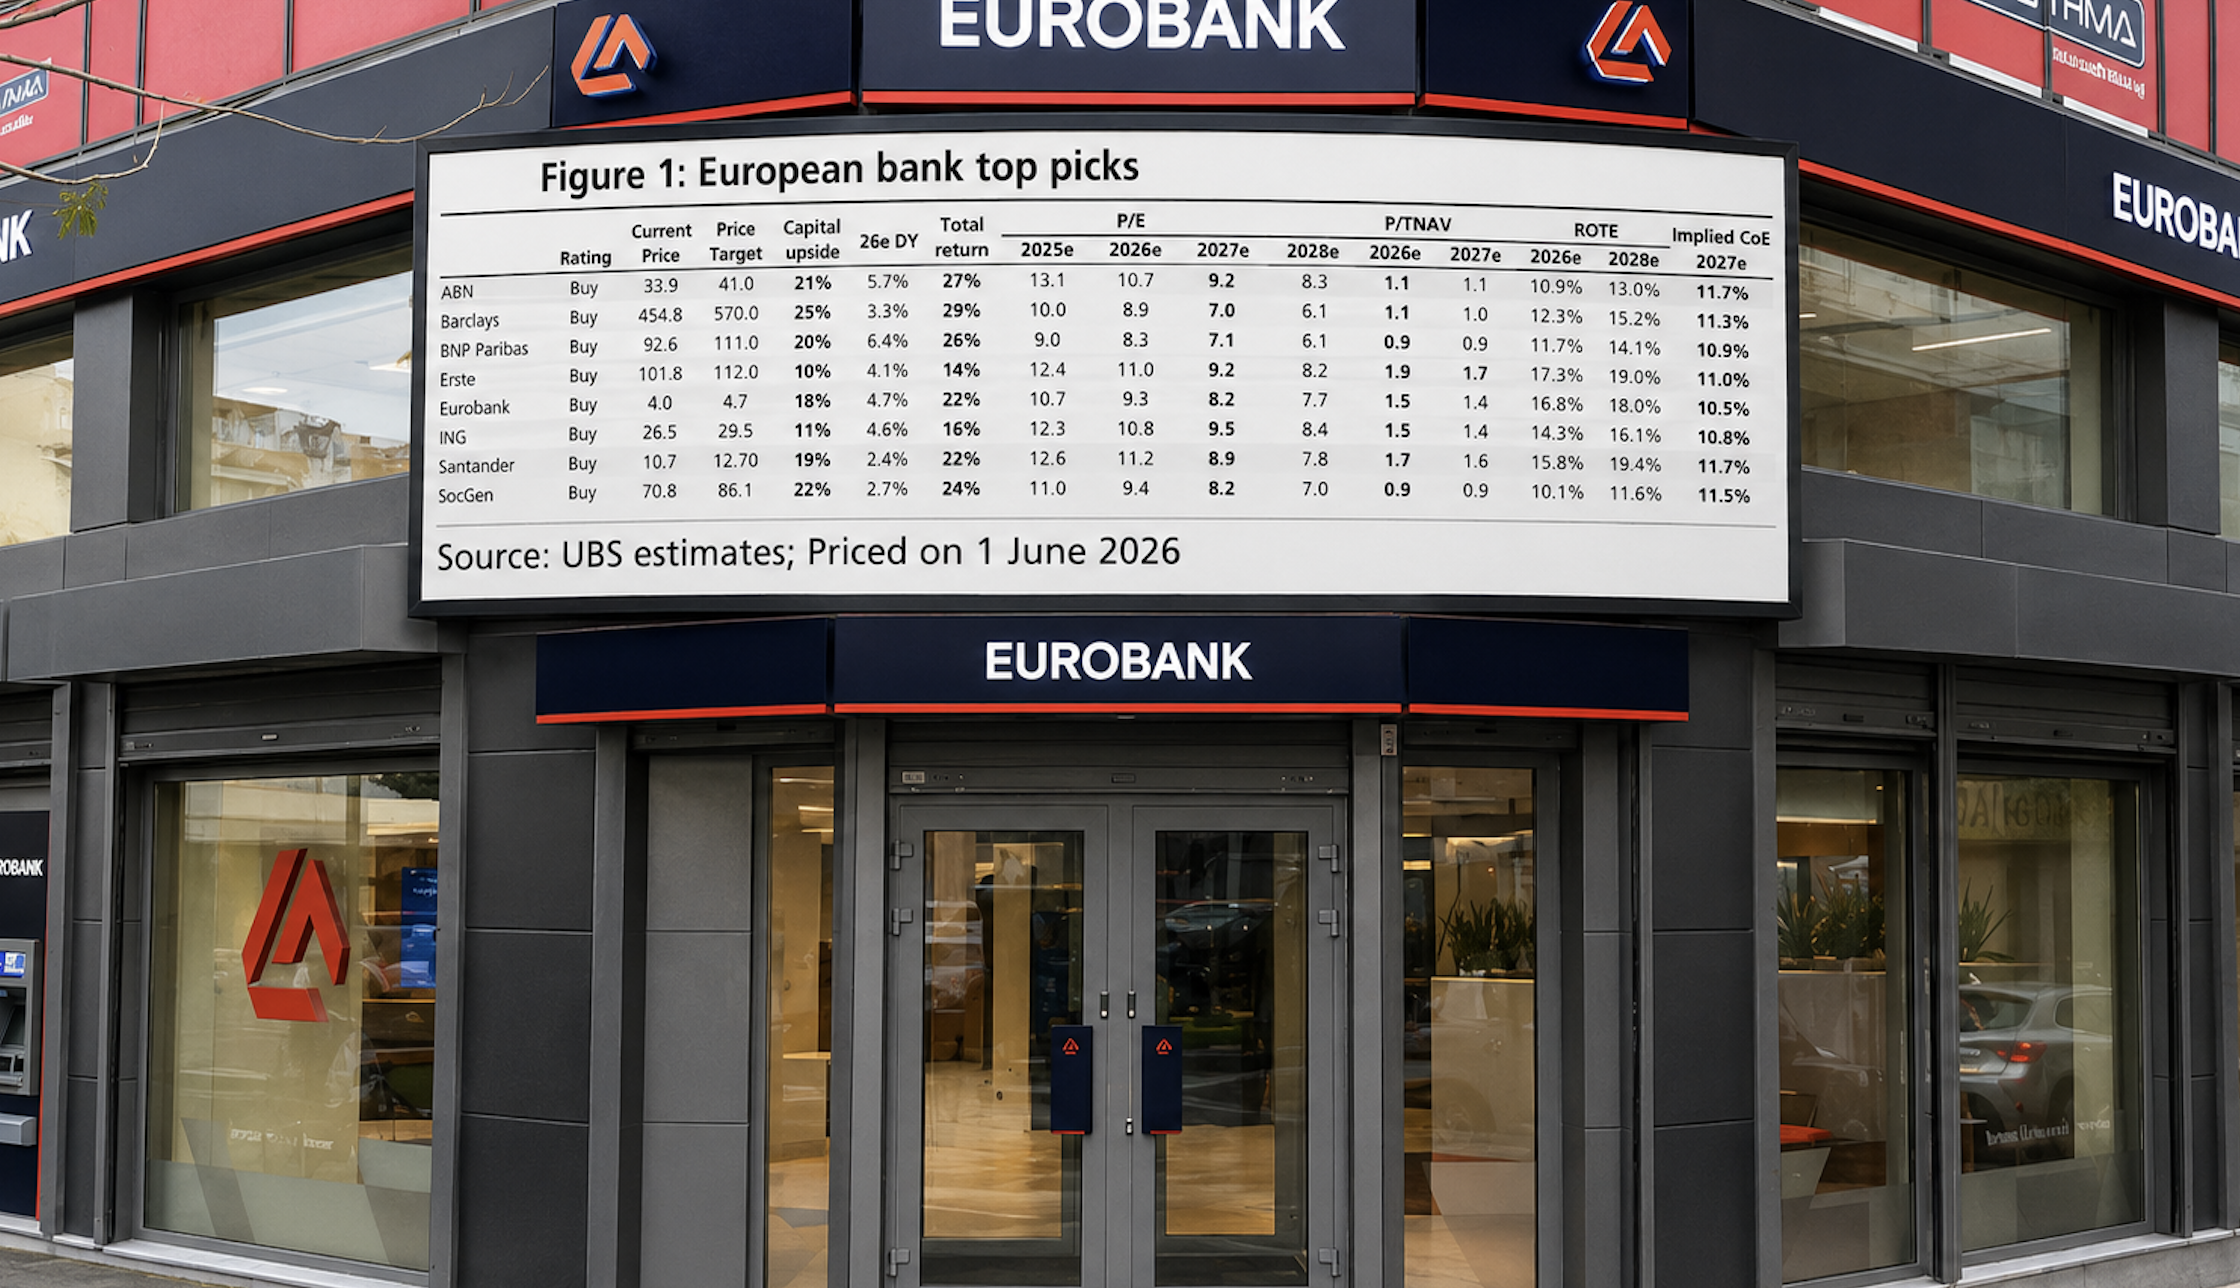
After a solid 1Q26 – 73% of banks beat consensus at a PBT level – aggregate market forecasts for 2026/7 EPS were largely unchanged last month (+0.1-0.3% MoM). That’s not unexpected, in our view, given i) the mix of the 1Q beats (mostly non-NII), ii) present macro uncertainty, and iii) a general lack of updates to FY26 guidance (a calendar thing: in this environment it’s sensible to leave updates until later despite some material 1Q beats (see StanChart at 1Q, for example)). We expect reassurance on operating trends from management at this week’s industry conference with targets updated at 2Q supporting further sector EPS upgrades. Near term we’re conditioned for a continuation of the status quo until resolution is achieved in the Middle East, with investors generally happy to keep the banks they have and disinclined to add more or others for now. We like European banks at 9.2x / 8.4x FY27/8 EPS, 7-8% distributed yield and positive gearing to higher-for-longer rates and well-supported loan and deposit growth.
Stable at a sector level, quite a lot going on under the surface
Overall EPS estimates were broadly stable in May. Revenues forecasts rose <1% MoM (NII and fees), costs +0.1% MoM and loan losses mixed but immaterially changed (+1% in 2026E, -2% in 2027E). Year to date therefore, we have the sector EPS up 3-5% in 2026 and 2027. Bloomberg Best EPS has banks upgraded by 9% YTD lagging only Oil & Gas (+50%), Basic Resources (+25%) and Tech (+20%). Within banks on Visible Alpha, data dispersion was high this month with StanChart (+6%), ABN (+5%), KBC (+5%) and Jyske (+4%) showing the largest FY27 upgrades, and Valiant (-5%), Komercni / ING / BNP (-4%) and SAB (-3%) the biggest cuts. Relative to Visible Alpha consensus we see upside risks to FY27 consensus at Raiffeisen (+23%), Valiant (+22%), EFG / NBG (+7%) and DB / OTP / Komercni (+4%), and downside risks for BAMI / Jyske (-6%) and BPER / SHB / BOI (-5%). Note the new table on consensus depth which is relatively low for Bawag, Komercni, EFG, Cembra, Valiant and OTP.
Valuation attractive, we maintain a diversified portfolio
European equities and the bank sector are both up 5% YTD with banks outperforming by ~3% since the conflict in the Middle East began. That makes sense, we think: the equity market assumes near term resolution (equities at all time highs) while energy prices, and AI, infrastructure, defence and greening spend inflation have all but removed the downside risks to rates. Our bear scenarios are: i) a substantial equity correction, and ii) a stagflationary episode so material as to force policy rates so high as to deliver a recession in the near term and rates below neutral thereafter, an outcome which we think could easily see banks 20-30% lower. Our base case, of a fairly brief energy shock, stable-to-slightly-higher policy rates and resilient macro, should position the sector well to continue to outperform, in our view.
 Προσθήκη του MarketsReport.gr στην Google