
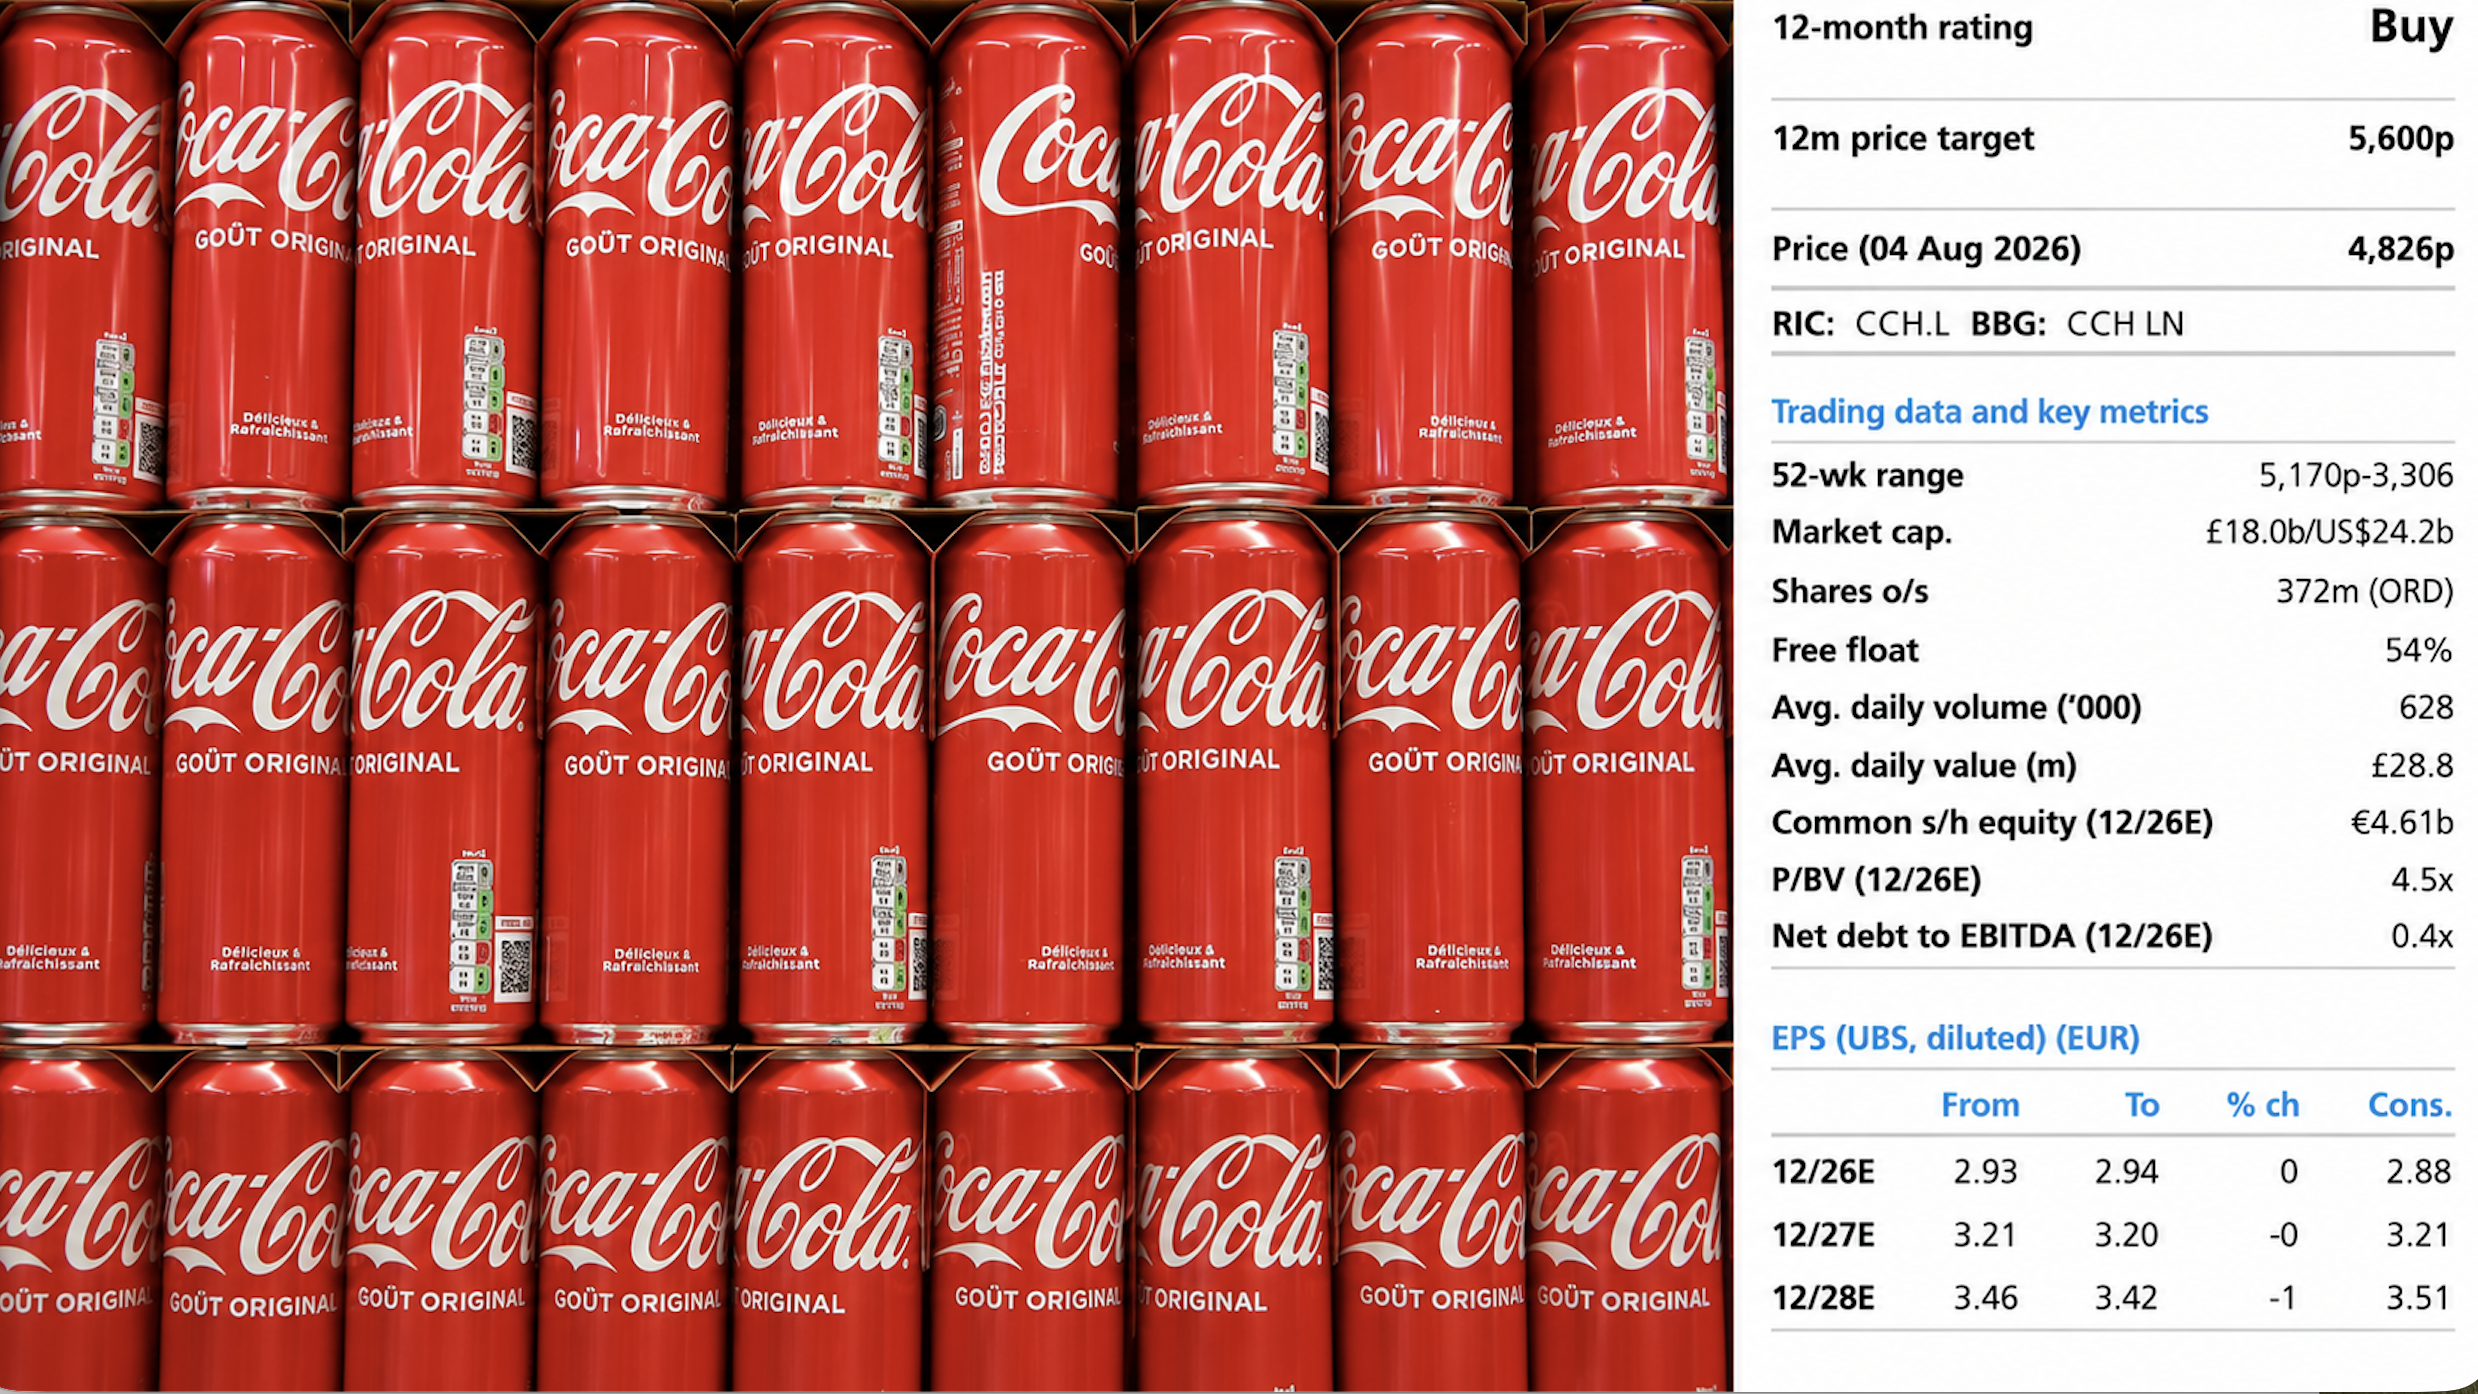
UBS view
CCH’s +c6% Q2 volume growth was the strongest since Q2 2018 (outside of the covid pandemic era), and best in class across global consumer staples peers through earnings season, supporting a guidance raise. Investor expectations had stepped up into these results on the back of the Coca-Cola Company’s strong print and own guidance raise, but the quantum and breadth of CCH’s beat across the regions should be taken well. The level of consistent volume growth warrants a premium multiple.
FY26 guidance raised: CCH raised FY26 org revenue guidance to the top-end of previous 6-7% range, and org EBIT has moved to 8-10% (from 7-10%). We think the outlook is potentially conservative, but prudent in light of volatile geopolitical backdrop and higher cogs outlook in H2 (unhedged energy costs). The outlook on net finance costs (now €40-50m from €45-65m) and FX (now flat to +€10m from flat to -€30m ) should also prompt +LSD% consensus EPS upgrades.
Strong, broad-based Q2 volume beat: CCH delivered Q2 +8% org. revenue, significantly ahead of company compiled cons +6.2%, with volumes +5.8% (cons +3.5%) ahead of expectations in all regions. Favourable weather trends were supportive, as well as the world cup and more moderating pricing; however, these results are another reminder of the superior embedded growth profile across CCH’s geographic footprint, to which CCBA should be accretive, and the consistency of execution (+80bps value share). We highlight; 1) Established (Q2 +3.4% vols v cons +1%) – Italy returned to +LSD% growth, complementing a positive contribution from all major markets in the region, with Switzerland and Austria positively inflecting; 2) Developing (Q2 +3.7% vols v cons +1.8%) – driven by continued +MSD% growth in Hungary, +HSD% in Czech and fading impact from DRS tax implementation in Poland; 3) Emerging (Q2 7.2% vols v cons +4.8%): Nigeria (+HSD%) and Egypt (+DD%) continued to outperform, however Russia also positively inflected (+HSD%).
Moderating pricing: Q2 price/mix +2.1% was below consensus +2.6% – although pricing came in ahead of expectations in Established and Developing markets, where category mix (Energy vols +26% in H1) and pack mix (single serve mix +110bps in H1) are favourable tailwinds, Emerging segment price/mix was weaker due to more moderate pricing as inflation is lower, and FX has been more favourable. We expect price/mix trends to pick-up in H2 on account of higher cogs outlook (unhedged energy costs).
Big EBIT beat from Emerging segment: H1 EBIT came in 4% above expectations, with org EBIT +15.2% (vs cons +11.9%), with strong operating leverage particularly on gross margin +110bps (predominantly Emerging segment), which helped support an uplift in marketing spend and deliver positive +60bps org EBIT margin expansion. Within the Emerging segment, we expect the main drivers to be strong margin recovery in Nigeria, as well as some benefit in Russia from favourable transactional FX. Overall, EPS came in 5% ahead of cons, also helped by lower net finance costs (higher interest income in Russia, and lower FX costs in Nigeria due to stronger FCF).
What are the negatives? 1) Weak margins driving EBIT miss in Established and Developing markets, in part due to increased marketing support; 2) Cash trapped in Russia increased to €1.04bn up from €850m at FY25; 3) FCF was -11% YoY, but due to phasing of capex, and was still ahead of consensus.
Valuation: CCH trades on 17.7x 2027E P/E and 18.1x EV/NOPAT, roughly in line with European Staples ex. Alcoholic drinks.

 Προσθήκη του MarketsReport.gr στην Google